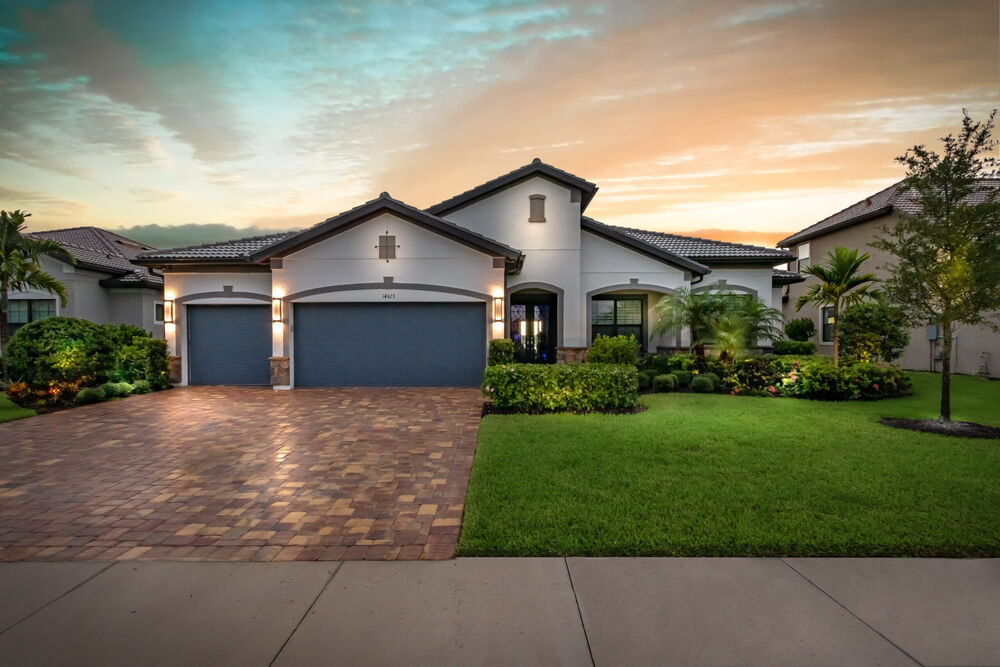
If you're thinking about selling your Southwest Florida home this summer, you've probably heard the objection: "Nobody buys during hurricane season." That's a myth, and a costly one if you believe it.
The truth? Summer 2026 buyers in SWFL are more serious, more decisive, and more motivated than their peak-season counterparts. They're here because they need to be, job relocations, life transitions, investment opportunities, not because they're casually browsing between snowbird activities. Your job as a seller is to position your home to meet them where they are.
Here's the complete playbook for selling your SWFL home during hurricane season in 2026.
The Summer Seller Reality: What the Data Actually Says
Let's start with real numbers. Summer does change the market, but not in the way most sellers fear:
- Buyer pool: 60-70% smaller than April peak, but 100% serious
- Days on market: Up from 16-18 days (April) to 28-38 days (June-August)
- Multiple offers: Drop from 60-70% of listings to 8-15%
- Negotiation room: Buyers expect 5-8% below asking vs. 0-2% in April
- Price reductions: 35-45% of summer listings see at least one reduction
The sellers who succeed in summer 2026 are the ones who price correctly from day one, prepare their homes for hurricane-season scrutiny, and market directly to the motivated buyer profile. Those who try to hold April pricing into July will sit and eventually chase the market down.
Who Is the Summer 2026 SWFL Buyer?
Understanding your buyer is the first step to closing. Summer buyers fall into five primary categories:
1. Job Relocators (Largest Segment)
Corporate transfers, healthcare workers moving to Lee Health or NCH, military personnel at Buckley/MacDill, and remote workers committing to full-time SWFL residency. These buyers must close by a specific date, often August 1-September 1. They are pre-approved, decisive, and will not play games on price if your home checks their boxes.
2. Estate & Life-Transition Sellers-Turned-Buyers
Families settling estates, divorces, and downsizers don't stop buying because it's June. This segment often needs to close quickly and is highly motivated on both sides of the transaction.
3. Investment Buyers
Summer is prime time for SWFL real estate investors. Lower competition, motivated sellers, and the ability to negotiate 5-8% below asking makes summer the best time to acquire rental properties. If your home has rental history or income potential, market it aggressively to this segment.
4. Snowbird Upgraders
Snowbirds who spent the season here in 2025-2026 and want to upgrade or buy a permanent residence often shop in summer when prices soften. They know the market, they have cash or strong pre-approval, and they're not intimidated by hurricane season because they've lived through it.
5. New-Construction Refugees
Buyers who were waiting on new construction and got burned by delays or price increases are re-entering the resale market in summer 2026. They want move-in-ready homes and will pay a slight premium for quality finishes and proven storm performance.
Pricing Your Home for Summer 2026: The Right Strategy
The #1 mistake SWFL sellers make in summer is pricing to April comps. Those numbers are real, but they're history. Summer buyers know it, and overpriced homes in summer SWFL don't just sit; they get stigmatized.
2026 Summer Pricing Benchmarks by Area:
- Cape Coral (Standard): $415K-$460K (April was $450K-$500K), expect 8-10% softening
- Cape Coral Waterfront: $540K-$660K (April was $575K-$700K), waterfront holds better; 5-7% softening
- Fort Myers: $355K-$405K (April was $385K-$440K), 7-9% softening typical
- Estero/Bonita Springs (Golf/Gated): $540K-$650K (April was $565K-$680K), lifestyle communities hold value; 4-6% softening
- Naples (Luxury $750K+): $720K-$1.05M range, ultra-luxury ($2M+) softens least; entry-luxury softens 8-12%
- Bonita Beach/Naples Beach: Beach-adjacent holds strong; 3-5% softening on beachfront, 6-10% on near-beach
Pricing Strategy: Come in 3-5% below your April comparable, price to sell in the first 21 days, and avoid the chasing pattern. A home that lists at $485K and sells at $470K is far better than a home that lists at $500K, sits 60 days, drops to $480K, and eventually sells at $462K with a stigma.
Hurricane-Proofing Your Listing: What Buyers Will Scrutinize
Post-Ian SWFL buyers are savvier than ever. They will ask about every storm-related item, and your answers, or your agent's inability to answer, will make or break deals. Get ahead of this:
🪟 Impact Windows & Doors
If you have full impact protection, lead with it. In your listing description, in your photos, in your MLS remarks. Impact windows reduce insurance costs $800-$2,000/year and are increasingly a buyer requirement. If you have shutters instead, document the full shutter system and have it inspected.
🏠 Roof Age & Condition
Roofs over 15 years old are a deal-killer in the current insurance environment. If your roof is 10-15 years old, get a pre-listing inspection and a letter from a licensed roofer confirming remaining life. If it's over 15, consider a proactive replacement, a new roof in SWFL adds $15K-$25K to sale price and eliminates the #1 buyer objection.
🔒 Open Permits
Post-Ian repairs often left open permits. Pull a permit history from your county before listing. Unresolved permits will be flagged in inspection and can kill a contract at the last minute. Close them proactively.
💧 Flood Zone Documentation
Know your FEMA flood zone designation. If you're in Zone X (low risk), market that aggressively, it's a premium. If you're in Zone AE, have your elevation certificate ready and a current flood insurance quote. Buyers will request it; be ready.
🌊 Waterfront: Seawall Certificate
If you're on a canal, gulf-access, or riverfront, get a seawall inspection and certificate before listing. A $800 seawall inspection that comes back clean saves your deal. One that reveals $40K in repairs needs to be addressed, or priced, before you hit the market.
🏦 Insurance: Be Transparent
Provide your current insurance premium in the listing package. Buyers are shocked by SWFL insurance costs when they're from out of state. Getting ahead of it, "current insurance $4,200/year with Citizens, impact windows, $3K hurricane deductible", builds trust and prevents last-minute shock.
The Pre-Listing Storm Readiness Package
The single most powerful thing a summer SWFL seller can do is create a Storm Readiness Package, a one-page document (or small binder) that gives buyers every storm-related data point they'll ask for. This package signals that you're a serious, transparent seller and eliminates the #1 source of summer deal friction.
Include in your Storm Readiness Package:
- Roof inspection report + age + warranty documentation
- Impact window/door brand, install date, certification
- Wind mitigation inspection report (reduces insurance cost; buyers love this)
- FEMA flood zone designation + elevation certificate
- Current flood insurance policy or quote
- Current homeowners insurance premium + carrier
- Seawall inspection certificate (waterfront only)
- Generator documentation (if applicable, a whole-house generator adds $8K-$15K of perceived value)
- Open permit verification (county pull, show it's clean)
- History of Ian-related repairs (if applicable) with permits and contractor documentation
Sellers who present this package at showing significantly reduce negotiation friction and inspection surprises. Buyers feel confident. Deals close.
Marketing to the Summer SWFL Buyer
Summer buyers aren't browsing Zillow on a Saturday morning like peak-season snowbirds. They're searching with intent, often remotely, and making faster decisions. Your marketing needs to meet them where they are:
Professional Video Tour: Non-Negotiable
Summer buyers are 40-60% more likely to be purchasing remotely or after only 1-2 in-person visits. A professional video walkthrough (not just photos) is essential. Highlight storm features: impact windows, new roof, generator, elevated construction.
3D Virtual Tour
Matterport or equivalent. Relocating buyers will make offers on homes they've only walked through virtually. This is table stakes for summer SWFL marketing in 2026.
Insurance & Carrying Cost Disclosure Up Front
Include estimated monthly costs in your listing remarks: mortgage at current rate, insurance, property taxes, HOA/CDD. This targets the serious buyer who's doing real math, not window shoppers.
Target the Relocator Directly
Ask your agent to run targeted Facebook and Instagram ads to the job-relocator profile: people who are moving from Northeast, Midwest, or West Coast cities with SWFL employers (Lee Health, NCH, Amazon, Gartner, and others with major SWFL presences). This is a sophisticated targeting layer that most agents skip.
List on a Tuesday or Wednesday
Summer buyers are on a faster timeline than peak-season buyers. Listing Tuesday-Wednesday gives you the full workweek for remote buyer consideration, allowing for weekend showing and offer by the following Monday-Tuesday. This beats the Friday-list/Saturday-surge pattern that works in April but falls flat in summer.
Staging for Summer: Outdoor Living Is Your Competitive Advantage
SWFL's biggest lifestyle draw, outdoor living, doesn't stop in summer. In fact, buyers imagining year-round Florida living are deeply influenced by outdoor spaces. Your pool, lanai, and outdoor kitchen aren't seasonal features; they're year-round selling points.
Summer Staging Priorities:
- Pool: Crystal clear, well-lit for evening photos. Pool cage in perfect condition (no torn screens, replace before listing). Show lifestyle, not maintenance.
- Lanai: Stage with tasteful outdoor furniture, plants, and string lights. This is where buyers emotionally buy the home.
- Landscaping: Summer is when SWFL landscaping is at peak green. Pressure wash the driveway, trim palms, and add fresh mulch. $500 in landscaping returns $3K-$5K in perceived value.
- Interior: Cool & Comfortable: Keep AC at 72°F for showings, not 78°F. Buyers come from hot outdoors; walking into a cool, comfortable home creates a positive emotional response that photos can't manufacture.
- Dehumidify: SWFL humidity can create musty odors in vacant or minimally occupied homes. Run a dehumidifier, check for moisture issues, and have HVAC serviced before listing.
Offer Strategy: How to Handle Summer Offers
Summer offers look different than April offers. Here's how to navigate them:
Expect Inspection Requests
Summer buyers negotiate on inspection results more aggressively than peak-season buyers. Pre-list inspection ($350-$500) eliminates this friction. Fix the obvious items (leaky faucets, minor HVAC issues, stuck windows/doors). Be ready to provide concessions on larger items rather than killing the deal.
Closing Timeline Flexibility
Relocating buyers often need flexible closing timelines (30-60 days). If you can offer flexibility, especially if you've already found your next home or are moving into a rental, advertise it. "Seller can accommodate 30-60 day closing" is a significant lever in summer negotiations.
Closing Cost Contribution
Summer buyers frequently ask for $5K-$10K in closing cost assistance. This is effectively a price reduction but preserves the sale price on paper (which matters for your comps). If you're priced correctly, a $7,500 closing cost contribution on a $450K home is a 1.6% concession, acceptable if it closes the deal.
Don't Counter Too High
Summer buyers are strategic. If they offer 6% below asking and you counter at full price, they move on, there's another motivated seller. A counter at 2-3% below asking is the right posture for serious summer negotiation.
2026 Summer Selling Timeline: Your Week-by-Week Plan
If you're selling this summer, here's a realistic timeline that works with hurricane season, not against it:
Weeks 1-2 (Now: June 11-25): Pre-listing preparation. Schedule roof inspection, wind mitigation inspection, and seawall inspection (if waterfront). Pull permit history. Stage outdoor areas. Get insurance quote for disclosure. Hire agent and finalize pricing strategy.
Weeks 3-4 (June 25-July 8): Professional photography and video tour. Complete Storm Readiness Package. List on MLS by June 30 to July is the best summer listing window (relocators finalizing August start dates).
Weeks 5-6 (July 8-21): Showings, open house (one weekend open house per week maximum), and offer collection. Target first offer by day 14-18 on market. If no offers by day 21, reassess price, don't wait 45 days.
Weeks 7-10 (July 21-August 15): Negotiate, inspect, and close. Target closing August 1-15 for relocating buyers with school-year move-in deadlines.
August 16-September 30 (Deep Hurricane Season): If your home is still on market, be aware this is the slowest window. Consider pulling temporarily and re-listing October 1 as peak season approaches, or aggressively reduce price to close before September.
The Storm Clause: What Sellers Need to Know
Florida real estate contracts have specific hurricane/storm provisions that summer sellers must understand:
- Property Damage Clause: Under the Florida AS-IS contract, if the property sustains casualty damage between contract and closing, the buyer can cancel and receive full deposit refund. This is non-negotiable, understand it before listing.
- Insurance During Contract: Maintain your current coverage through closing. Do not cancel or reduce your policy the moment you go under contract.
- Named Storm Delay: Many contracts include a 7-day delay provision for named storms that affect the subject property area. Build this into your closing timeline expectations.
- Active Storm Watch: Showings typically stop 48-72 hours before a forecasted storm impact. Build buffer into your showing schedule during active tropical weather periods.
Real Example: Summer Sale vs. Waiting Until October
Here's the math SWFL sellers need to run before deciding to wait for peak season:
Scenario: $500,000 Estero home, listed June 2026
- Summer list price: $475,000 (5% below April comp)
- Summer sale price: $462,000 (2.7% below list after closing cost concession)
- Carrying costs June-October (mortgage, insurance, taxes, HOA): ~$8,500/month = $34,000
- Net summer: $462,000 + save $34,000 in carrying costs = $462,000 + no carrying cost drain
Scenario: Same home, waiting for October 2026 peak season
- October list price: $495,000 (recovering toward spring comps)
- October sale price: $485,000 (market still building toward January peak)
- Carrying costs paid June-October: $34,000
- Net October: $485,000 - $34,000 carrying costs = $451,000 net
Result: Selling in summer 2026 nets $11,000 MORE than waiting for October, and eliminates 4 months of hurricane season exposure, market uncertainty, and carrying cost stress.
Ready to Sell Your SWFL Home This Summer?
Hurricane season doesn't have to mean a bad sale. It means a smarter strategy, a prepared home, and an agent who knows exactly how to reach the motivated buyer pool that exists in June-August 2026.
At Gulf Pointe | eXp Realty, we've helped SWFL homeowners close successful summer sales by combining data-driven pricing, comprehensive storm readiness preparation, and targeted marketing to relocating and investor buyers who are actively looking right now.
Contact Brad Dohack at Gulf Pointe | eXp Realty, call 239.494.5156 or visit liveswfl.com to get your free summer sale strategy consultation today.